Propel Financing Requirements, Rates and Eligibility

Everything Concert Finance actually requires to write a Propel loan, and everything the program will and will not cover. Credit thresholds, term options, project limits, property and roof eligibility, and the timing windows that catch people out.

35–40%
Max Discount, PV + Storage
$0
Dealer Fee Markup
8.99%*
APR at time of writing
CA CO TX
Now Live in Colorado
Compare Propel vs. Participate
⚡
Concert Finance Partner
|
⭐
BBB A+ Rated
|
✅
No Dealer Fee Inflation
|
🏠
Ownership at Year 5
|
🔒
Fixed Payment, No Escalator
How It Works

The Propel Financing Mechanism, Step by Step

Concert Finance uses a commercial ownership structure to unlock federal tax credits no longer available to residential homeowners. Those savings are passed to you as a real, upfront discount before any loan amount is set.

1

Concert Finance Takes Temporary Title

For years one through five, Concert Finance holds commercial ownership of the solar system. This structure qualifies the system for commercial-tier Section 48E Investment Tax Credits unavailable to residential buyers.

2

The Propel Discount Is Applied First

The credit value is passed to you as an upfront discount before the loan is calculated — up to 20% on a PV-only system, and up to 35–40% when battery storage is included, with Energy Community and domestic content bonuses stacking on top. You borrow a genuinely reduced amount from day one, not an inflated one.

3

You Pay One Fixed Monthly Rate

Your Propel payment is set at 8.99% APR, on a term you choose from 5 to 25 years. No escalator, no dealer markup buried in the balance, no surprises at year five or year fifteen.

4

Full Ownership Transfers at Year 5

At the five-year mark, the system is yours outright. It adds to your home's assessed value and produces power at zero marginal cost for the remaining life of the panels.

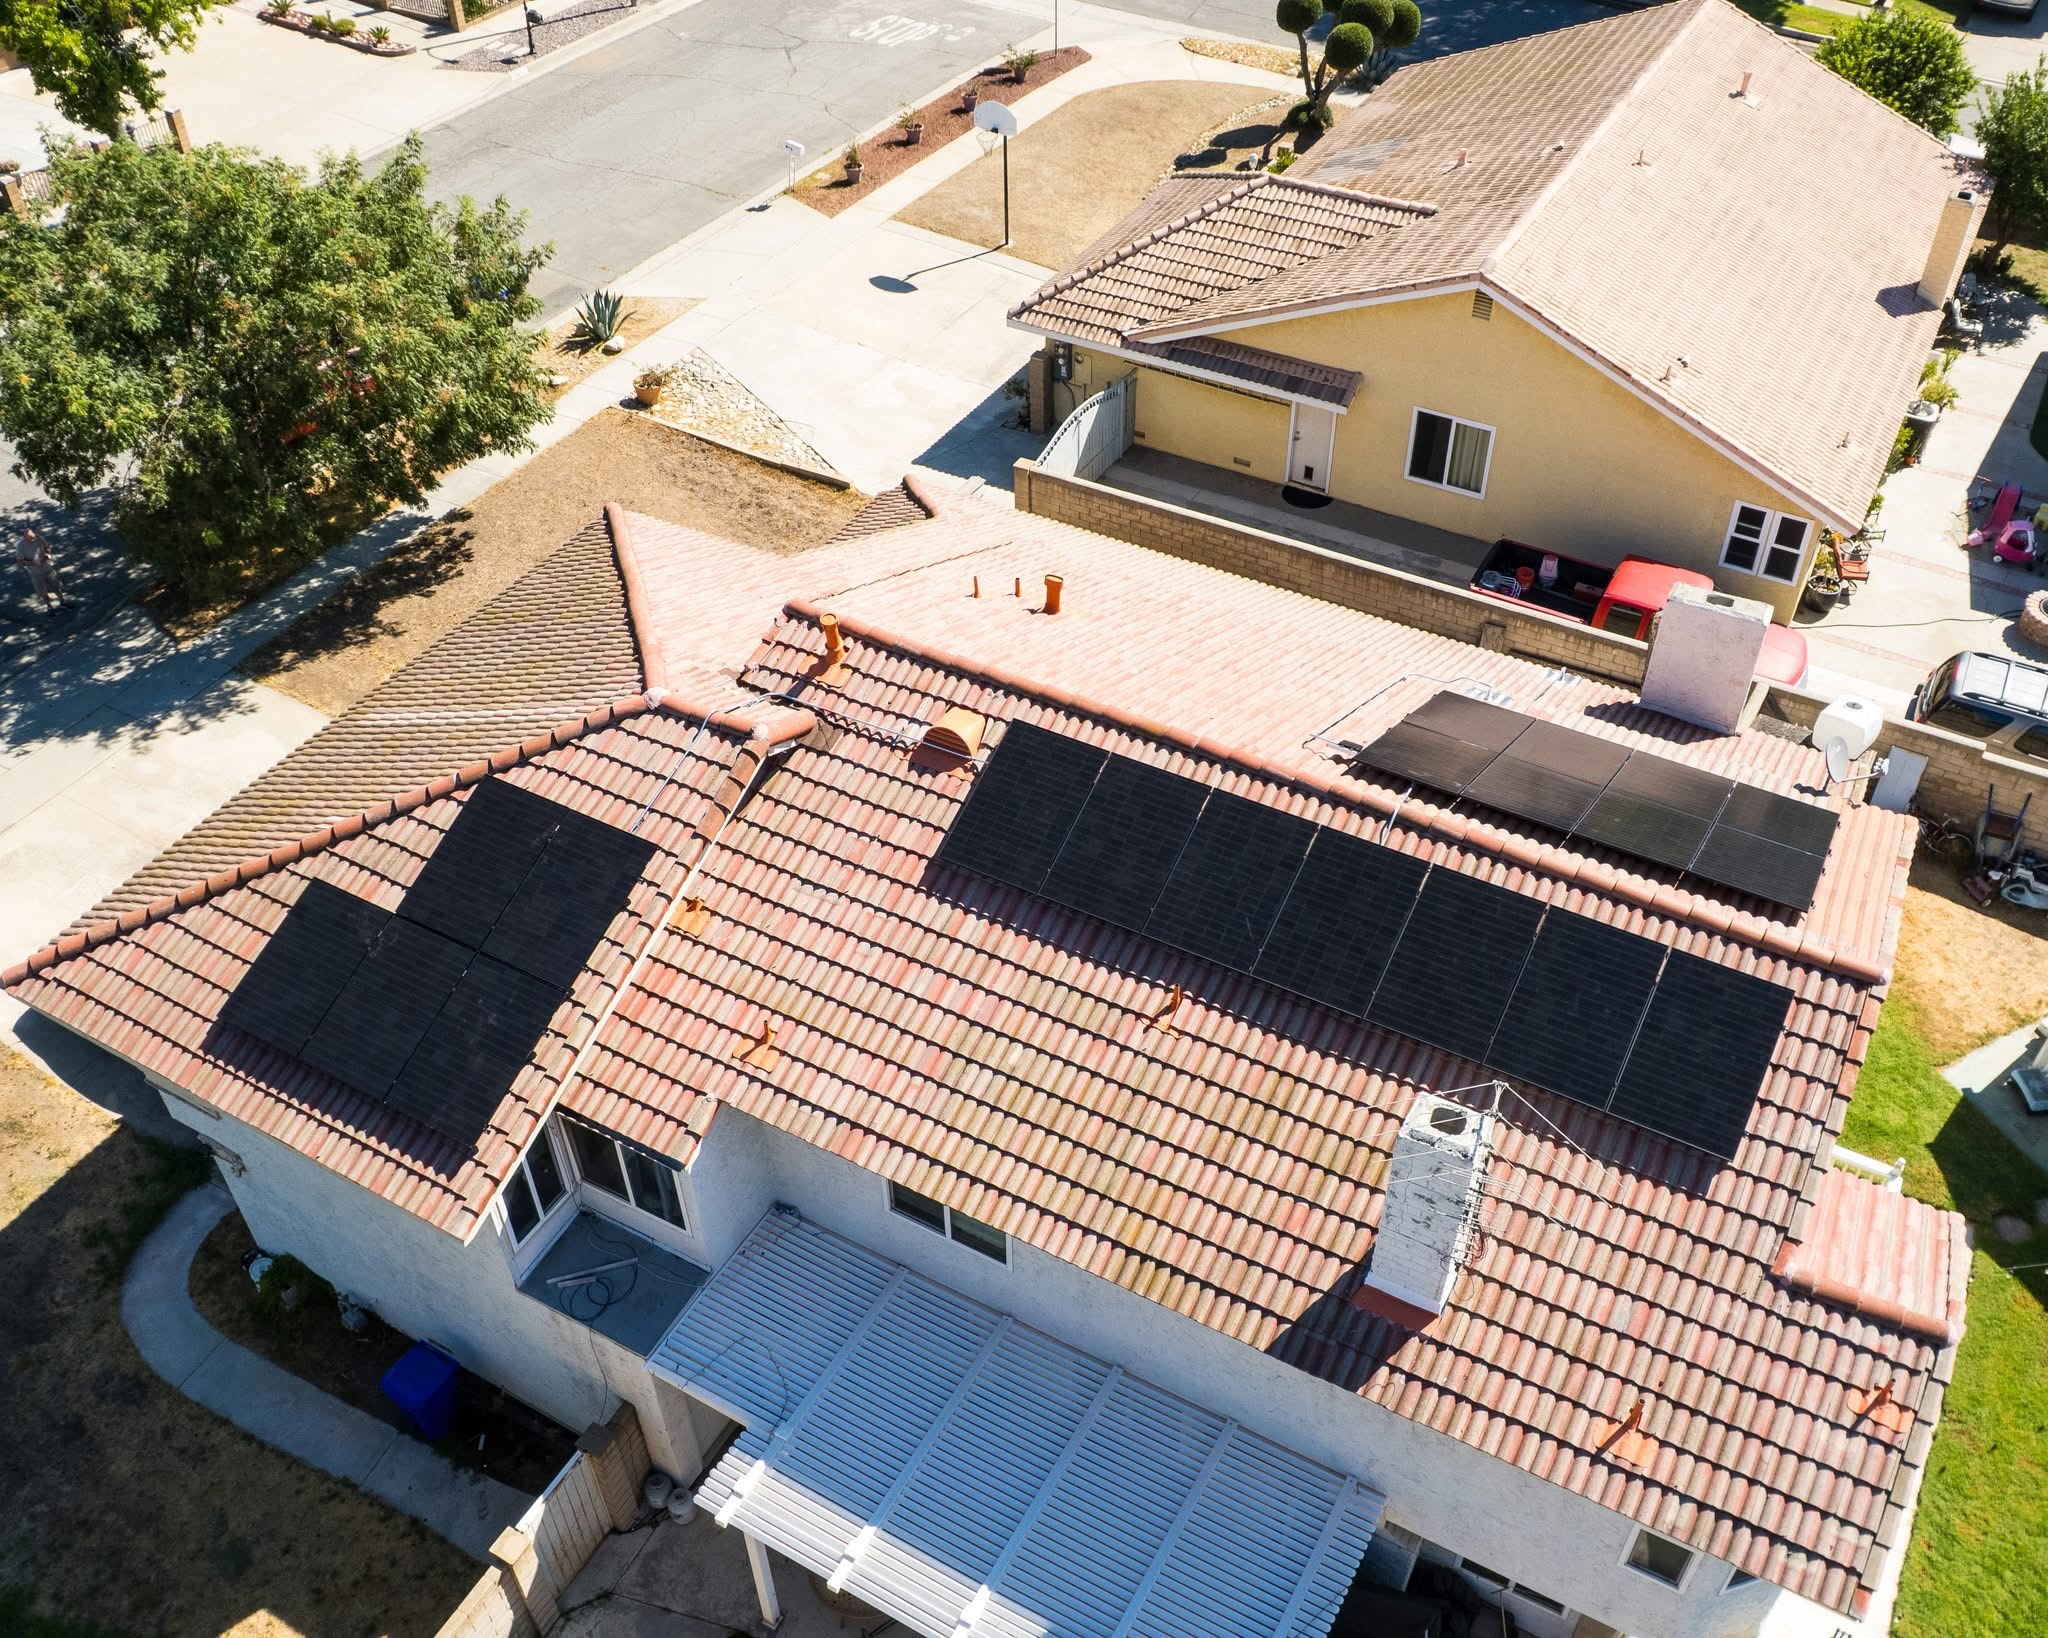
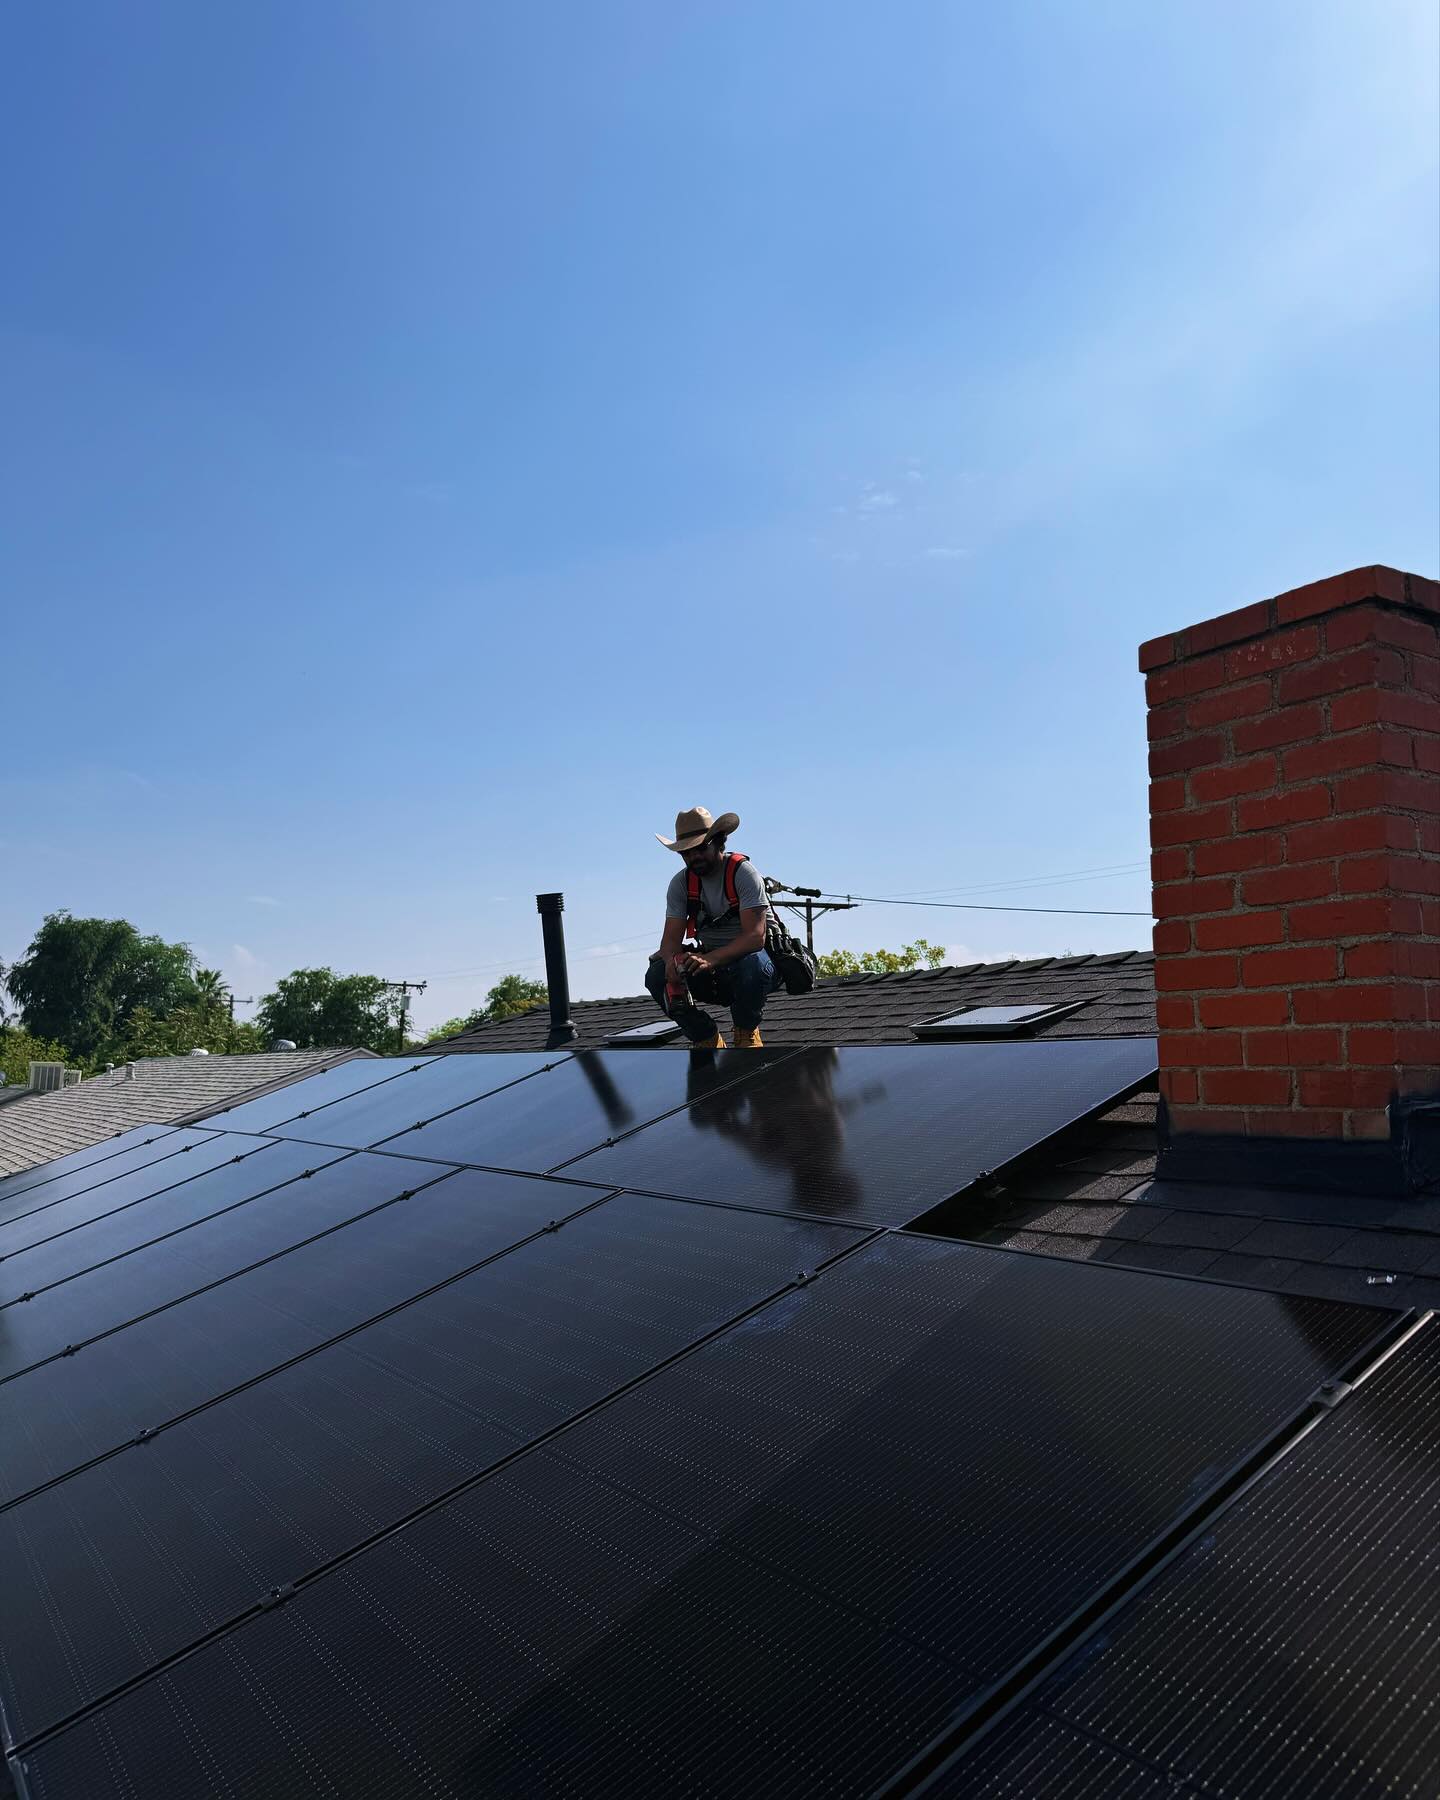
Aerial view of a California home with rooftop solar financed through Propel
Product Details

What Makes Propel Different from Every Other Solar Loan

Built by Concert Finance exclusively for authorized partners. These are terms your neighbors won't find on a standard solar loan application.

Discount

Up to 35–40% With Storage

Applied before financing. A PV-only system earns up to 20%. Adding battery storage raises the ceiling to 35–40%, and Energy Community and domestic content bonuses stack on top — a project qualifying for both can reach 37% or more.

Payments

Fixed Payment, 5 to 25 Years

8.99% APR* on a term you choose, from 5 years up to 25. Your Propel rate today is your rate in year 20. No escalator, no rate resets, no surprises.

Eligibility

660 FICO, TransUnion Only

Concert pulls TransUnion only, with a 660 minimum. Once you are approved, the loan must be signed within 60 days, and the credit approval stays valid for 180 days in total.

Ownership

System Transfers at Year 5

Concert Finance holds temporary commercial title, then full ownership transfers to you at the five-year mark with no additional out-of-pocket cost.

Flexibility

No Prepayment Penalty

Pay off the loan early at any time. Accelerate ownership on your schedule with zero exit fees.

Reamortization

Up to 3 Reamortizations

Restructure the loan balance at months 12, 24, and 36. This is rare in the solar lending market and lets you lower your monthly payment with a lump-sum contribution.

No Dealer Fees

Zero Dealer Fee Markup

Most solar loans inflate the financed amount with 20-30% dealer fees. Propel charges none. You borrow the real system cost.

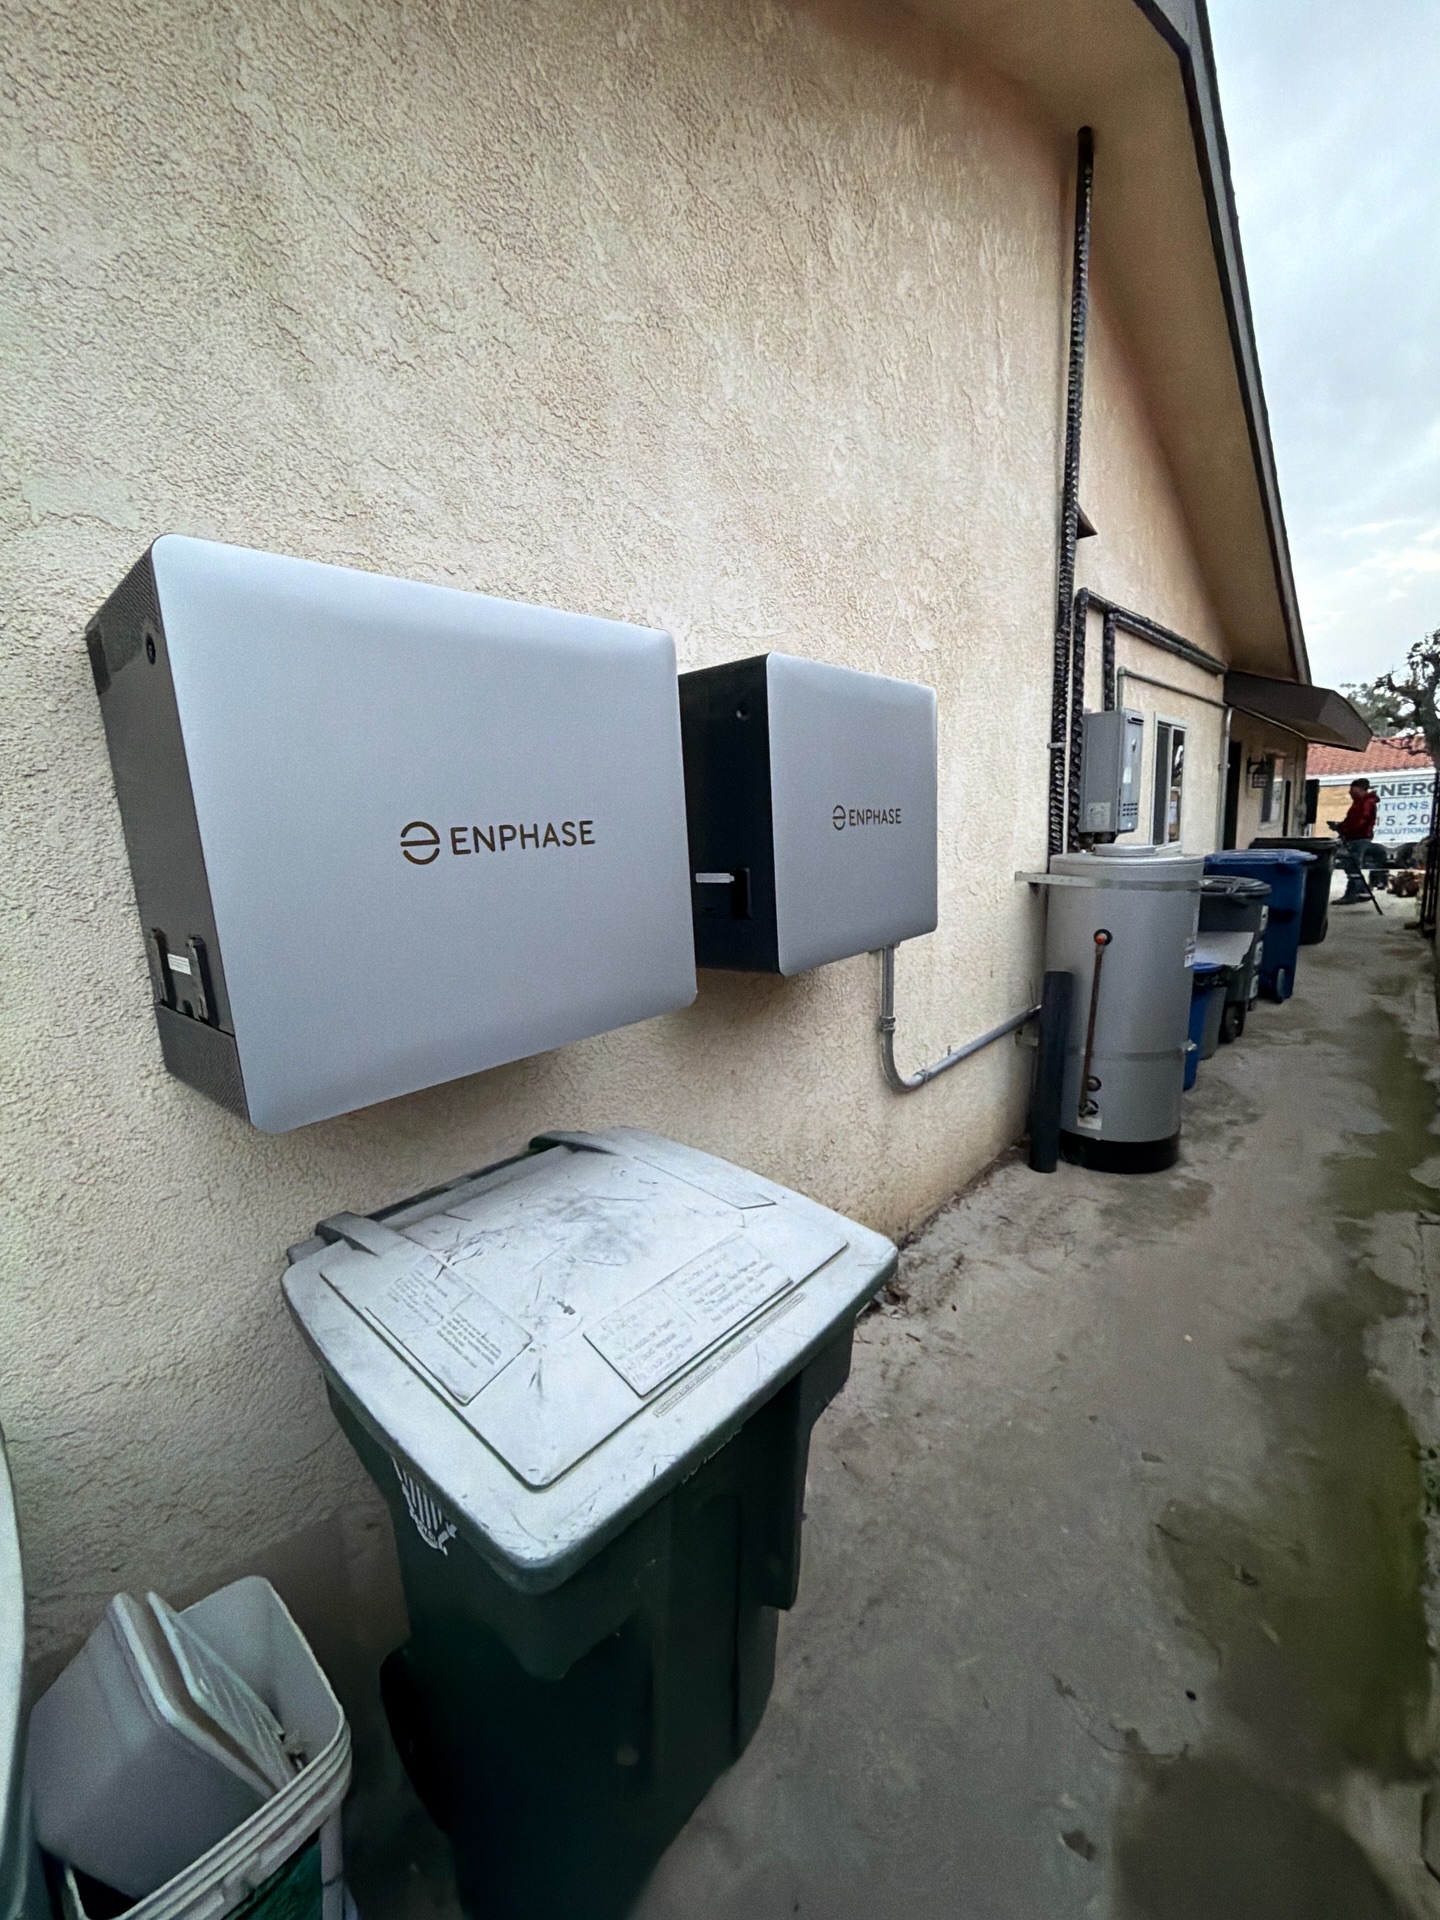
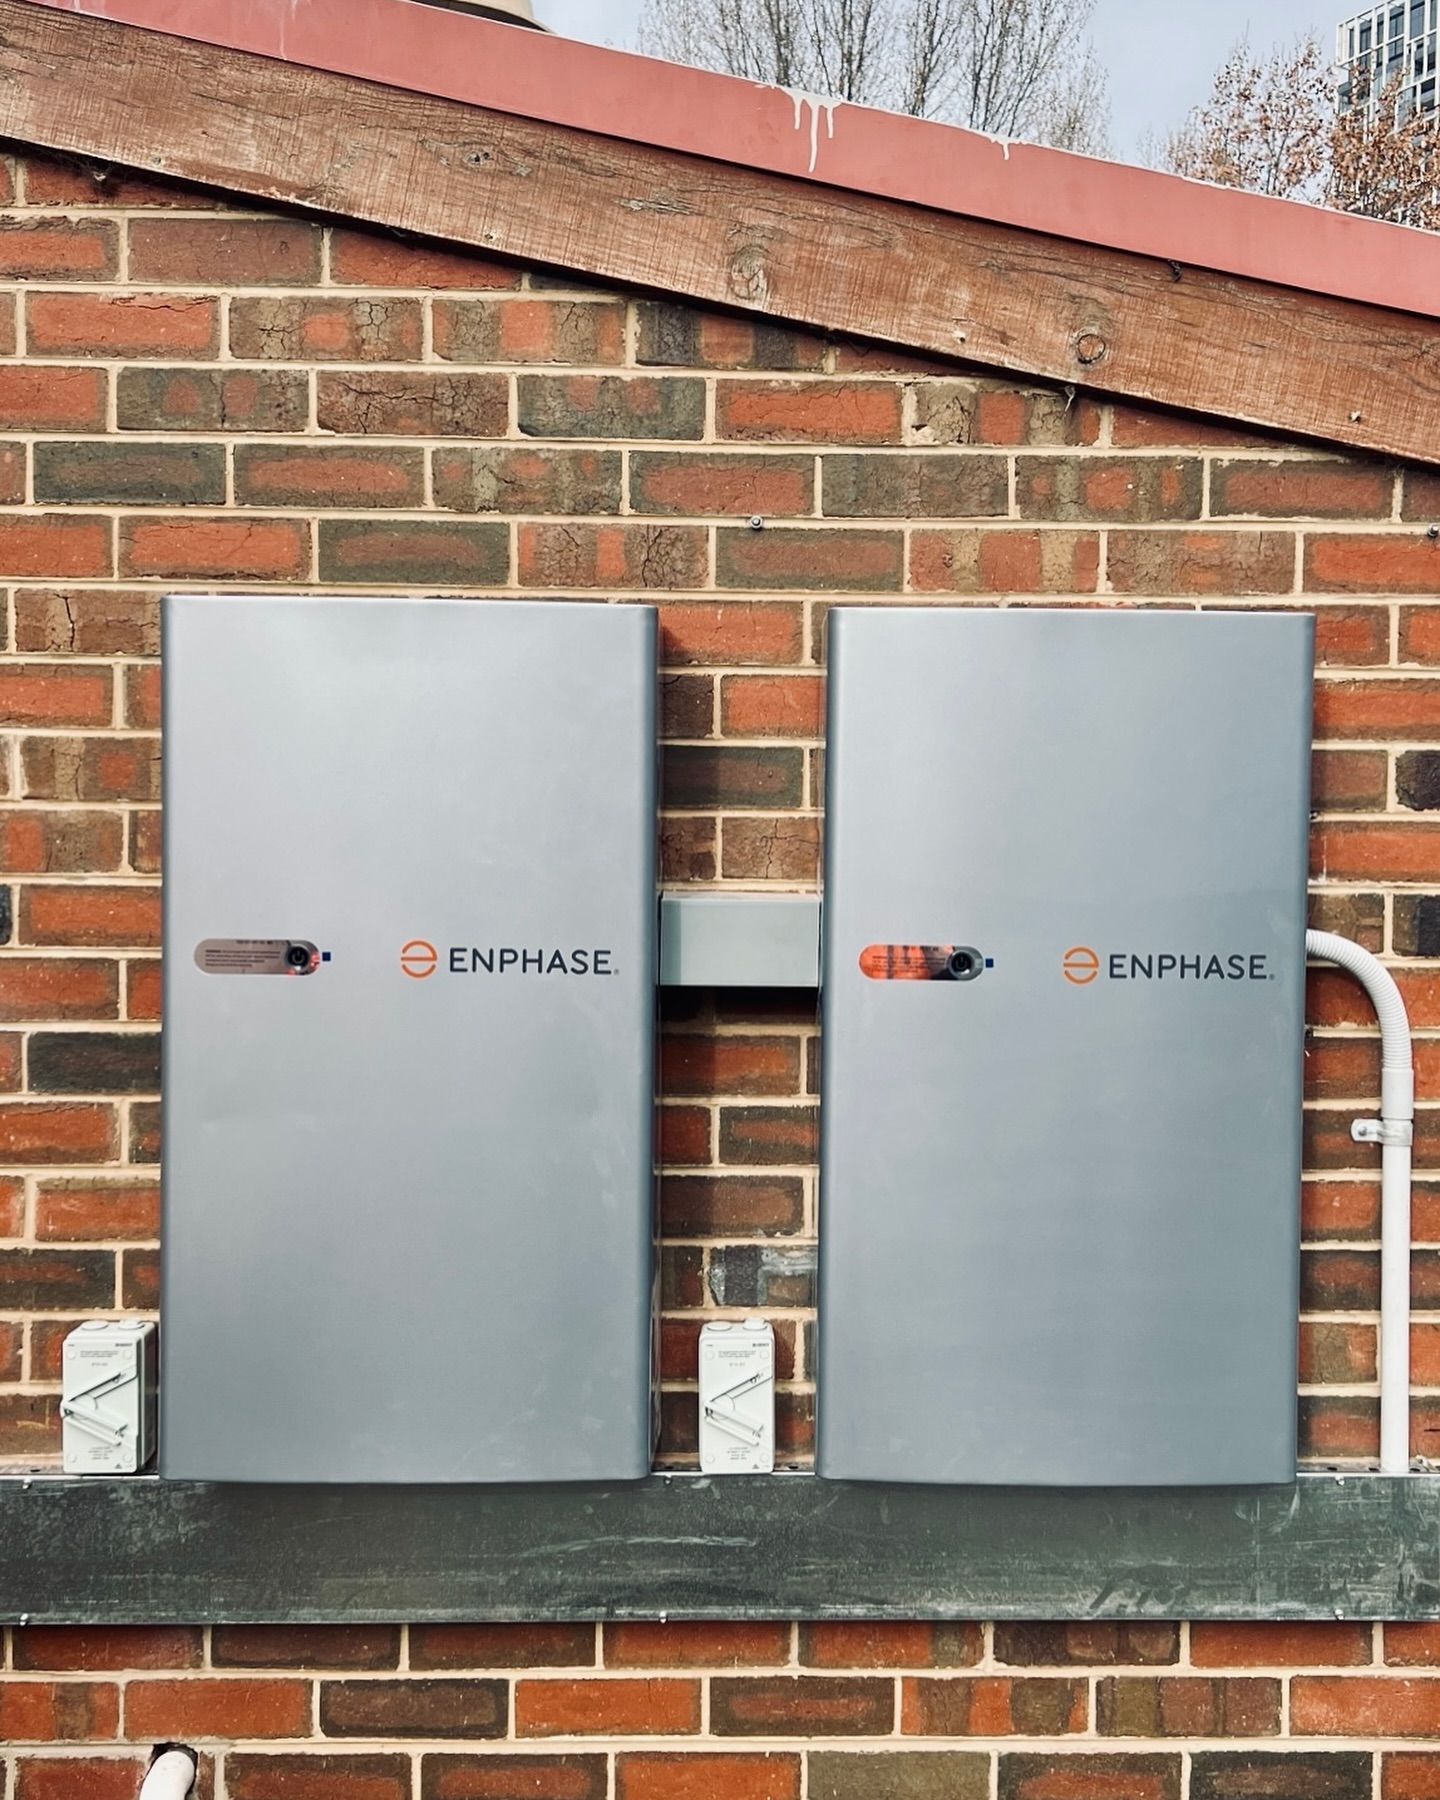
Pair of Enphase IQ batteries mounted outdoors on a home exterior wall, the storage hardware included in Propel Financing solar packages
Side-by-Side Comparison

Propel vs. Traditional Solar Loan vs. Monthly PPA/Lease

A low year-one payment is not the same as the best 25-year outcome. Here is what the math actually looks like across the most common solar financing options available to California homeowners today.

Feature ⚡ Propel by Concert Finance Traditional Solar Loan Monthly PPA / Lease
Upfront cost to start$0 to startOften required or inflated$0 to start
Upfront discount appliedUp to 20% PV only, 35–40% with storageNoneNone to homeowner
Dealer fees in priceZero dealer markupOften 20-30% addedN/A
Payment escalationFixed for 25 yearsFixed1-3% per year common
System ownershipTransfers at year 5Immediate (inflated price)May never own
Prepayment penaltyNoneOften yesN/A
Tax credit accessUp to 35–40% via commercial structureResidential ITC expired 2025Not available to homeowner
Credit check requiredYes, 660 FICO minimumYes, typically 680+Varies by provider
Home sale complexitySimple, tied to borrowerSimpleLease transfer required

← Scroll on mobile to see all columns

Real California Homeowners

What Propel Financing Actually Looks Like on a Proposal

These are real numbers from finalized Propel proposals. Monthly payments and discount amounts vary based on system size, utility territory, and Energy Community status.

Cervera Family
Kernville, CA — Energy Community Zip
Utility Bill Before
$443
per month
Propel Payment
$271
per month, fixed
Propel Discount Applied$22,827
EC Discount Rate39.2%
Projected 25-Yr Savings$146,000
$172/mo
immediate monthly relief vs. current utility bill
Giron Family
Ojai, CA
Utility Bill Before
$500
per month
Propel Payment
$274
per month, fixed
Propel Discount Applied$23,059
Monthly Savings vs. Bill$226/mo
Projected 25-Yr Savings$194,000
$194K
projected 25-year advantage over staying on the grid
Wais Family
Corona, CA
Utility Bill Before
$781
per month
Propel Payment
$348
per month, fixed
Propel Discount Applied$28,867
Monthly Savings vs. Bill$433/mo
Projected 25-Yr Savings$303,000
$303K
projected 25-year advantage over staying on the grid

Savings projections model 6% annual utility rate escalation based on historical CA averages. Actual results vary. These are historical proposals; current Propel discount tiers are set by whether the system includes storage, plus Energy Community and domestic content bonuses, so your figures may differ. Discount amounts are finalized at signing.

Solar panel and battery installation on a California rooftop
Discount Tiers

How the Propel Discount Is Calculated

The single biggest factor is whether your system includes battery storage. A PV-only system earns up to 20%. Adding storage raises the ceiling to 35–40%. From there, IRS Energy Community status and domestic content each add a bonus, and a project qualifying for both can reach 37% or more. Propel passes that value to you as an upfront discount before any financing is calculated.

Solar + Battery Storage
35–40%

Including battery storage in the system raises the discount ceiling to 35–40%. This is the single largest lever on your Propel number, and it is worth modelling even if a battery was not in your original plan.

Energy Community and domestic content bonuses stack on top of this. A project qualifying for both can reach 37% or more. Your advisor confirms your exact zip against the IRS database before the proposal is built.

PV Only, No Storage
Up to 20%

A solar-only Propel system earns up to 20%. That is a genuine discount applied before financing, but it is roughly half what the same project earns once storage is added.

If you are comparing a PV-only Propel quote against a Participate prepaid lease, this is usually the reason the numbers diverge. We run both.
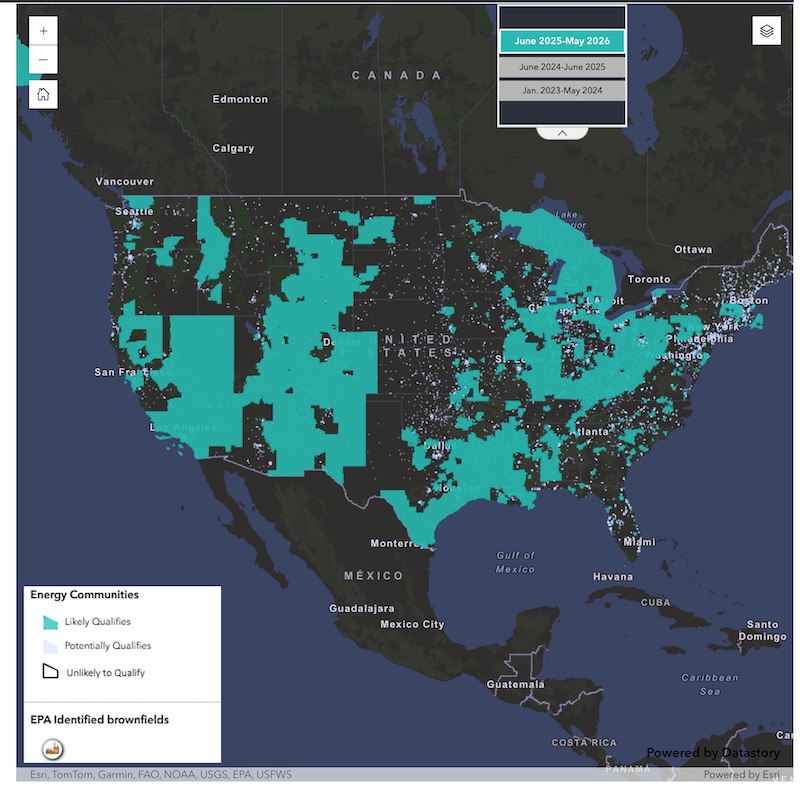
Not sure which tier applies to your home? Your advisor checks your exact zip code against the IRS Energy Community database, and confirms which equipment qualifies as domestic content, before any proposal is built. Both bonuses are reflected in your numbers automatically.
IRS Energy Community bonus tax credit map showing California Energy Community zip codes eligible for 39.2% Propel Financing discount

IRS Energy Community designation map. EC zip codes unlock a bonus adder that stacks on top of the storage and domestic content tiers.

See how Propel vs. Participate compares specifically in California →
Program Terms

Propel Financing: Full Terms at a Glance

The complete published terms of the Propel loan, including the caps and eligibility rules that decide whether a project can actually be written. Most surprises late in a solar deal come from this table, not from the pricing.

TermPropel by Concert Finance
Product typeLoan
Discount / rebateUp to 20% on PV only. Up to 35–40% on PV plus storage. Energy Community and domestic content bonuses may apply, and a project qualifying for both can reach 37% or more.
Dealer feeNone
Loan terms5 to 25 years at 8.99% APR
FICO requirement660 minimum, pulled from TransUnion only
Project cap$10,001 minimum to $135,000 maximum. The loan must be signed within 60 days of credit approval, and the approval is valid for 180 days in total.
Price-per-watt capCalifornia: $4.85/W (PV). Texas: $3.60/W (PV). Add $2,000/kWh for battery storage on either.
System size5 panels / 2 kW minimum
Second systemsAllowed as a completely separate system. Non-export systems are not permitted.
Eligible property typesSingle-family residential on a permanent foundation. Manufactured homes built after 6/15/1976 are eligible. Multi-unit properties up to 4 units, where separate deeds mean separate loans. New construction is not eligible before occupancy.
Roof restrictionsNot allowed: copper, slate, spray foam, wood shake, and reverse tilt.
Ground mountsNot available
OccupancyPrimary, rental, vacation and secondary residences all qualify. Trusts, LLCs and corporations are allowed subject to criteria. Tribal land is not eligible.
Leased landAllowed, with a 99-year minimum lease.
Spanish-language contractsNot available
States availableCalifornia, Colorado and Texas. Colorado is newly live.
*
Rates and discount tiers change, and Propel's have been moving upward. Every APR, discount percentage and payment figure on this page reflects the program terms we had on record at the time of writing, and the rate quoted on a proposal issued today may be higher. Pricing is locked when your loan is signed, not when you first see a number, so the practical advice is to move while a quote is live.

Terms reflect the Propel program as of 2026 and are subject to change. Your specific discount, term and pricing are finalized at application and confirmed on your proposal before you sign anything.

How Propel and Participate differ on eligibility: Propel accepts manufactured homes built after 6/15/1976, multi-unit properties up to 4 units, and leased land on a 99-year minimum. Participate does not accept manufactured homes at all, but has no project cap and no system size limit, and offers Spanish-language contracts. Neither program does ground mounts without a battery. If one program cannot write your project, the other often can.
Enphase battery storage included in Propel solar packages
Common Questions

What Homeowners Ask About Propel by Concert Finance

Is Propel a loan or a lease?
Propel is a loan. It is not a monthly lease or a PPA, and there is no escalator. You choose a term between 5 and 25 years at 8.99% APR, and you can pay the balance off early at any time without penalty.
How is the Propel discount calculated?
The largest factor is whether the system includes battery storage. A PV-only system earns up to 20%. Adding storage raises the ceiling to 35-40%. On top of that, IRS Energy Community status and domestic content each add a bonus, and a project qualifying for both can reach 37% or more. The discount is applied to the system price before the loan amount is calculated, so you finance a genuinely reduced number.
Why is my PV-only quote so much lower than the headline discount?
Because the headline figure assumes storage. Solar-only Propel projects are capped at up to 20%, while solar plus storage reaches 35-40%. If you were quoted a PV-only system and the discount looked underwhelming, adding a battery is usually the single most effective change you can make to the economics. We will model it both ways so you can see the difference in dollars rather than percentages.
What are the Propel loan terms and rate?
Terms run from 5 to 25 years at 8.99% APR, with no dealer fee and no prepayment penalty. Loan amounts run from a $10,001 minimum to a $135,000 maximum. Once your credit is approved, the loan must be signed within 60 days, and the approval remains valid for 180 days in total.
Does Propel require a credit check?
Yes. Propel is a loan and requires a minimum 660 FICO score, pulled from TransUnion only. That threshold is lower than most traditional solar lenders. If you do not meet it, Participate Energy's Prepaid Lease is worth considering, since the lease itself has no FICO requirement when prepaid in cash.
What is the minimum system size?
5 panels, or 2 kW, whichever applies to your design. There is also a $10,001 minimum loan amount, so very small projects generally will not qualify.
What property types qualify for Propel?
Single-family residences on a permanent foundation. Manufactured homes qualify if built after June 15, 1976, which is a meaningful advantage over Participate, where manufactured homes are not eligible at all. Multi-unit properties up to 4 units qualify, though separate deeds mean separate loans. New construction is not eligible until the home is occupied.
Does the home have to be my primary residence?
No. Primary, rental, vacation and secondary residences all qualify. Trusts, LLCs and corporations are allowed subject to criteria. Tribal land is not eligible. Leased land is allowed with a 99-year minimum lease term.
What roof types are not allowed?
Copper, slate, spray foam, wood shake, and reverse tilt roofs are not eligible for Propel. Ground-mounted arrays are also not available under this program.
Can I add Propel if I already have solar?
Yes, as a completely separate second system. Non-export systems are not permitted under the program.
Which states is Propel available in?
California, Colorado and Texas. Colorado is newly live. If you are outside those three states, Participate Energy's prepaid lease covers eight states and is usually the alternative to look at.
Are Spanish-language contracts available?
Not for Propel. If Spanish-language documents are important, Participate Energy does provide them.
Can I pay off Propel early?
Yes, with no prepayment penalty. You can pay down or pay off the full balance at any time. The loan also allows up to three reamortizations at months 12, 24 and 36, which reduce your monthly payment when you apply a lump sum to the principal.
What happens if I sell my home?
Propel is a loan tied to you as the borrower rather than a lien attached to the property, so at sale the loan is settled much like other personal financing. That is considerably simpler than transferring a monthly PPA or lease, which requires the buyer to qualify and formally assume the agreement.
How does Propel compare to Participate Energy's Prepaid Lease?
Propel is a loan with a 660 FICO minimum, a $135,000 project ceiling, and a discount that depends heavily on including storage. Participate is a prepaid lease with no FICO requirement on the lease itself, no project or system size caps, a 30-35% discount set by domestic content, and an all-cash option with no monthly payment. Propel accepts manufactured homes and multi-unit properties; Participate does not. We run both and show you the numbers side by side.
What hardware is included with Propel?
Propel jobs through our installer network are built on Qcells 410W panels with Enphase IQ8HC microinverters. Battery storage uses Enphase IQ batteries. All equipment carries manufacturer warranties backed by the installing contractor.
What is the typical breakeven on Propel?
For most California homeowners with utility bills above $200 per month, the breakeven falls between years 6 and 8. After breakeven, savings compound as your fixed Propel payment stays constant while utility bills keep rising at roughly 6% per year historically.
See all Propel Financing FAQs →

Your Utility Bill Went Up Again This Year.
Your Propel Payment Won't.

Get a custom Propel Financing proposal built from satellite imagery of your roof, your exact utility rate, and your actual energy usage. Free and specific to your home.
Takes 2 minutes · 660 FICO required · No door-knock follow-up